Payment Processing in Logistics
An overview of payment processing, its significance in logistics, historical development, core concepts, and best practices.
Updated
Payment Processing in Logistics
Overview
Payment processing refers to the handling of financial transactions between parties within the supply chain and logistics sectors. This critical function ensures that payments for goods, services, and associated logistics operations (like freight, warehousing, and customs) are securely processed, confirmed, and recorded. Effective payment processing is essential for maintaining healthy cash flow for all stakeholders, optimizing operational efficiency, and ensuring the smooth flow of goods. In logistics, its reliability directly contributes to timely shipment and delivery, ultimately enhancing customer satisfaction and trust across the entire supply chain.
Etymology and Origins
The term "payment processing" encompasses two distinct historical concepts. The word payment originates from the Old French paiement, meaning "satisfaction, recompense," which itself is derived from payer (to pay). This can be traced back to the Latin pacare, meaning "to pacify, appease, satisfy" [7]. Over time, it evolved to specifically mean the satisfaction of a debt or obligation, often with money [8].
The concept of processing in a computational or systemic sense emerged much later. While rudimentary forms of record-keeping and exchange have existed for millennia, the modern understanding of "processing" financial transactions started to gain traction with the advent of automated systems. This began with mechanical accounting systems in the late 19th and early 20th centuries, followed by electronic data handling. The integration of "payment" and "processing" as a unified concept became prominent with the rise of electronic payments in the mid-20th century, particularly with the introduction of credit cards and subsequent digital transaction technologies [9]. These innovations necessitated systematic methods to manage and verify the increasing volume and complexity of non-cash transactions, laying the groundwork for modern payment processing systems.
Historical Development
Payment processing has evolved significantly from manual ledger entries to sophisticated digital networks:
- Pre-20th Century: For centuries, logistics payments were predominantly cash-based, followed by promissory notes, checks, and manual invoicing. This required extensive paper trails, reconciliation, and often led to significant delays in payment cycles [10].
- 1950s: The Dawn of Electronic Payments: The first widely accepted credit card, the Diners Club card, was introduced in 1950, marking the start of modern electronic payment systems. This innovation, pioneered by Frank McNamara and Ralph Schneider, allowed businesses to consolidate payments and individuals to pay for services across multiple merchants with a single card [11].
- 1960s-1970s: Automation and Electronic Funds Transfer (EFT): The establishment of early electronic funds transfer (EFT) systems in the 1960s and 70s allowed funds to be moved between bank accounts electronically. Key developments included the creation of the Society for Worldwide Interbank Financial Telecommunication (SWIFT) in 1973 for international wire transfers and the Automated Clearing House (ACH) network in the U.S. in 1974 for batch processing of debits and credits [12]. Concurrently, Electronic Data Interchange (EDI) emerged as a standard for B2B document exchange, including invoices and payment orders, revolutionizing how logistics companies managed transaction data [13].
- 1980s: Point-of-Sale (POS) and Early Integration: The proliferation of Point-of-Sale (POS) terminals in retail and widespread adoption of debit cards further digitized consumer transactions. Financial modules began to be integrated into early Enterprise Resource Planning (ERP) and Warehouse Management Systems (WMS), laying the groundwork for more holistic financial management within logistics operations.
- 1990s: The Internet Boom and E-commerce: The commercialization of the internet facilitated online payments. Companies like PayPal emerged in 1998, providing secure e-commerce solutions that dramatically simplified online transactions and spurred the growth of digital retail logistics [14]. This decade also saw the initial development of security standards for card data, leading to the eventual formation of PCI DSS.
- 2000s and Beyond: Mobile, Real-time, and Enhanced Security: The rise of mobile payments, digital wallets (e.g., Apple Pay, Google Pay), and contactless technologies (e.g., NFC) transformed how transactions are processed, reducing friction and enhancing user experience. Real-Time Gross Settlement (RTGS) systems became more prevalent globally, enabling instant settlement of high-value payments. The Payment Card Industry Data Security Standard (PCI DSS) was formally established in 2004 to protect cardholder data, becoming a critical compliance framework for any entity handling payment information [15].
- 2010s-Present: Distributed Ledgers and AI: The last decade has seen the emergence of advanced technologies like blockchain for transparent and secure transaction records, and AI/Machine Learning for enhanced fraud detection and risk assessment [16]. These innovations continue to shape the payment landscape, pushing logistics companies towards more secure, efficient, and integrated financial processes. The concept of embedded finance is also gaining traction, where financial services are seamlessly integrated into non-financial platforms, making payments an intrinsic part of the logistics workflow.
Core Concepts
Payment processing integrates several important components that work in concert to facilitate transactions:
- Payment Gateway: A specialized service that securely captures payment information, encrypts it, and routes it to the payment processor. It acts as a digital bridge between the merchant's application (e.g., an e-commerce website or a logistics platform) and the acquiring bank, ensuring authorization requests are transmitted and responses received [17].
- Payment Processor: The central intermediary between the payment gateway, merchant account, and the card networks (Visa, Mastercard, etc.). It manages the entire transaction flow: transmitting data, handling fraud checks, communicating with issuing banks for authorization, and facilitating the settlement of funds. Major payment processors include Stripe, Adyen, and Square.
- Merchant Account: A specific type of bank account that allows a business to accept payments made by credit cards, debit cards, or other electronic payment methods. Funds from customer transactions are temporarily held in this account before being transferred (settled) into the business's primary bank account [18].
- Acquiring Bank (Merchant Bank): The financial institution that holds the merchant account and processes credit and debit card transactions on behalf of the merchant. It receives authorized transaction requests from the payment processor and deposits funds into the merchant's account.
- Issuing Bank (Cardholder's Bank): The financial institution that issued the credit or debit card to the customer. It approves or declines transactions based on factors like available funds, credit limit, and fraud indicators, and ultimately disburses funds to the acquiring bank during the settlement process.
Modern systems are built to support diverse payment methods, including credit cards, debit cards, mobile wallets, bank transfers (ACH, SEPA, wire transfers), and even cryptocurrencies, adapting to consumer preferences and technological advancements. Integrating these payment systems with core logistics platforms, such as an Order Management System or a Purchase Order Management system, is crucial for end-to-end financial visibility.
Types and Classifications
Payment processing solutions can be classified based on their timing, frequency, and transaction type:
- Batch Payment Processing: Transactions are collected and processed in groups (batches) at specific intervals, typically once a day. This method is often used for payroll, scheduled billing, or bulk freight invoices where immediate settlement is not critical. While cost-effective, it results in delays between transaction initiation and final settlement.
- Real-time Payment Processing: Enables instant transaction completion and immediate settlement of funds, often within seconds. This is critical for e-commerce, expedited freight services, or last-mile delivery payments, where immediate confirmation enhances customer satisfaction and operational agility [19]. Examples include FedNow in the US and SEPA Instant in Europe.
- Recurring Payments: Automated processing for subscriptions, regular service contracts, or installment plans. This streamlines payment management for businesses and consumers alike, particularly for long-term logistics contracts, SaaS logistics solutions, or monthly warehousing fees. Examples include membership fees for freight networks or recurring lease payments for equipment.
- Point-of-Sale (POS) Payments: Transactions initiated in a physical location using terminals for credit/debit cards or mobile devices. In logistics, this applies to payments at freight depots, for C.O.D. (Cash on Delivery) services, or for on-site services like equipment maintenance.
- Online/E-commerce Payments: Transactions conducted over the internet, typically through payment gateways integrated into websites or mobile apps. This is fundamental for online retailers managing orders and for logistics providers offering digital booking and payment for shipping services.
- Business-to-Business (B2B) Payments: Often larger in value and more complex, B2B payments frequently involve invoicing, purchase orders, extended payment terms, and various payment methods like ACH, wire transfers, or virtual cards. Purchase Order Management systems often interface directly with these B2B payment methods.
Industry Applications
Payment processing plays a crucial role across various sectors within the supply chain and logistics ecosystem:
- E-Commerce and Retail Logistics: Online retailers rely heavily on seamless and secure payment processing for customer transactions, refunds, and chargebacks. Efficient payment systems are directly linked to customer conversion rates and the ability to process returns quickly, which impacts reverse logistics operations [20]. An integrated Pick, Pack, Ship Software solution often requires smooth payment confirmation before order release.
- Manufacturing and Procurement: Manufacturers and their suppliers must efficiently process supplier invoices, manage early payment discounts, and handle payments for raw materials, components, and finished goods. Robust payment systems, often linked to Purchase Order Management and ERP, ensure smooth procurement cycles and maintain strong vendor relationships.
- Transportation and Freight Logistics: Freight forwarders, carriers, and 3PLs utilize specialized payment systems to manage receivables for shipping services (e.g., freight charges, fuel surcharges, detention fees) and to pay vendors for services like port fees, customs duties, and intermodal transport. Automated freight audit and payment solutions are common to ensure accuracy and compliance [21].
- Warehousing and Distribution: Warehousing companies need efficient systems to bill clients for storage, handling, and value-added services. Payment processing for inbound (receiving goods) and outbound (shipping goods) operations is integrated into Visual Inventory Management Systems to ensure financial records align with physical inventory movements.
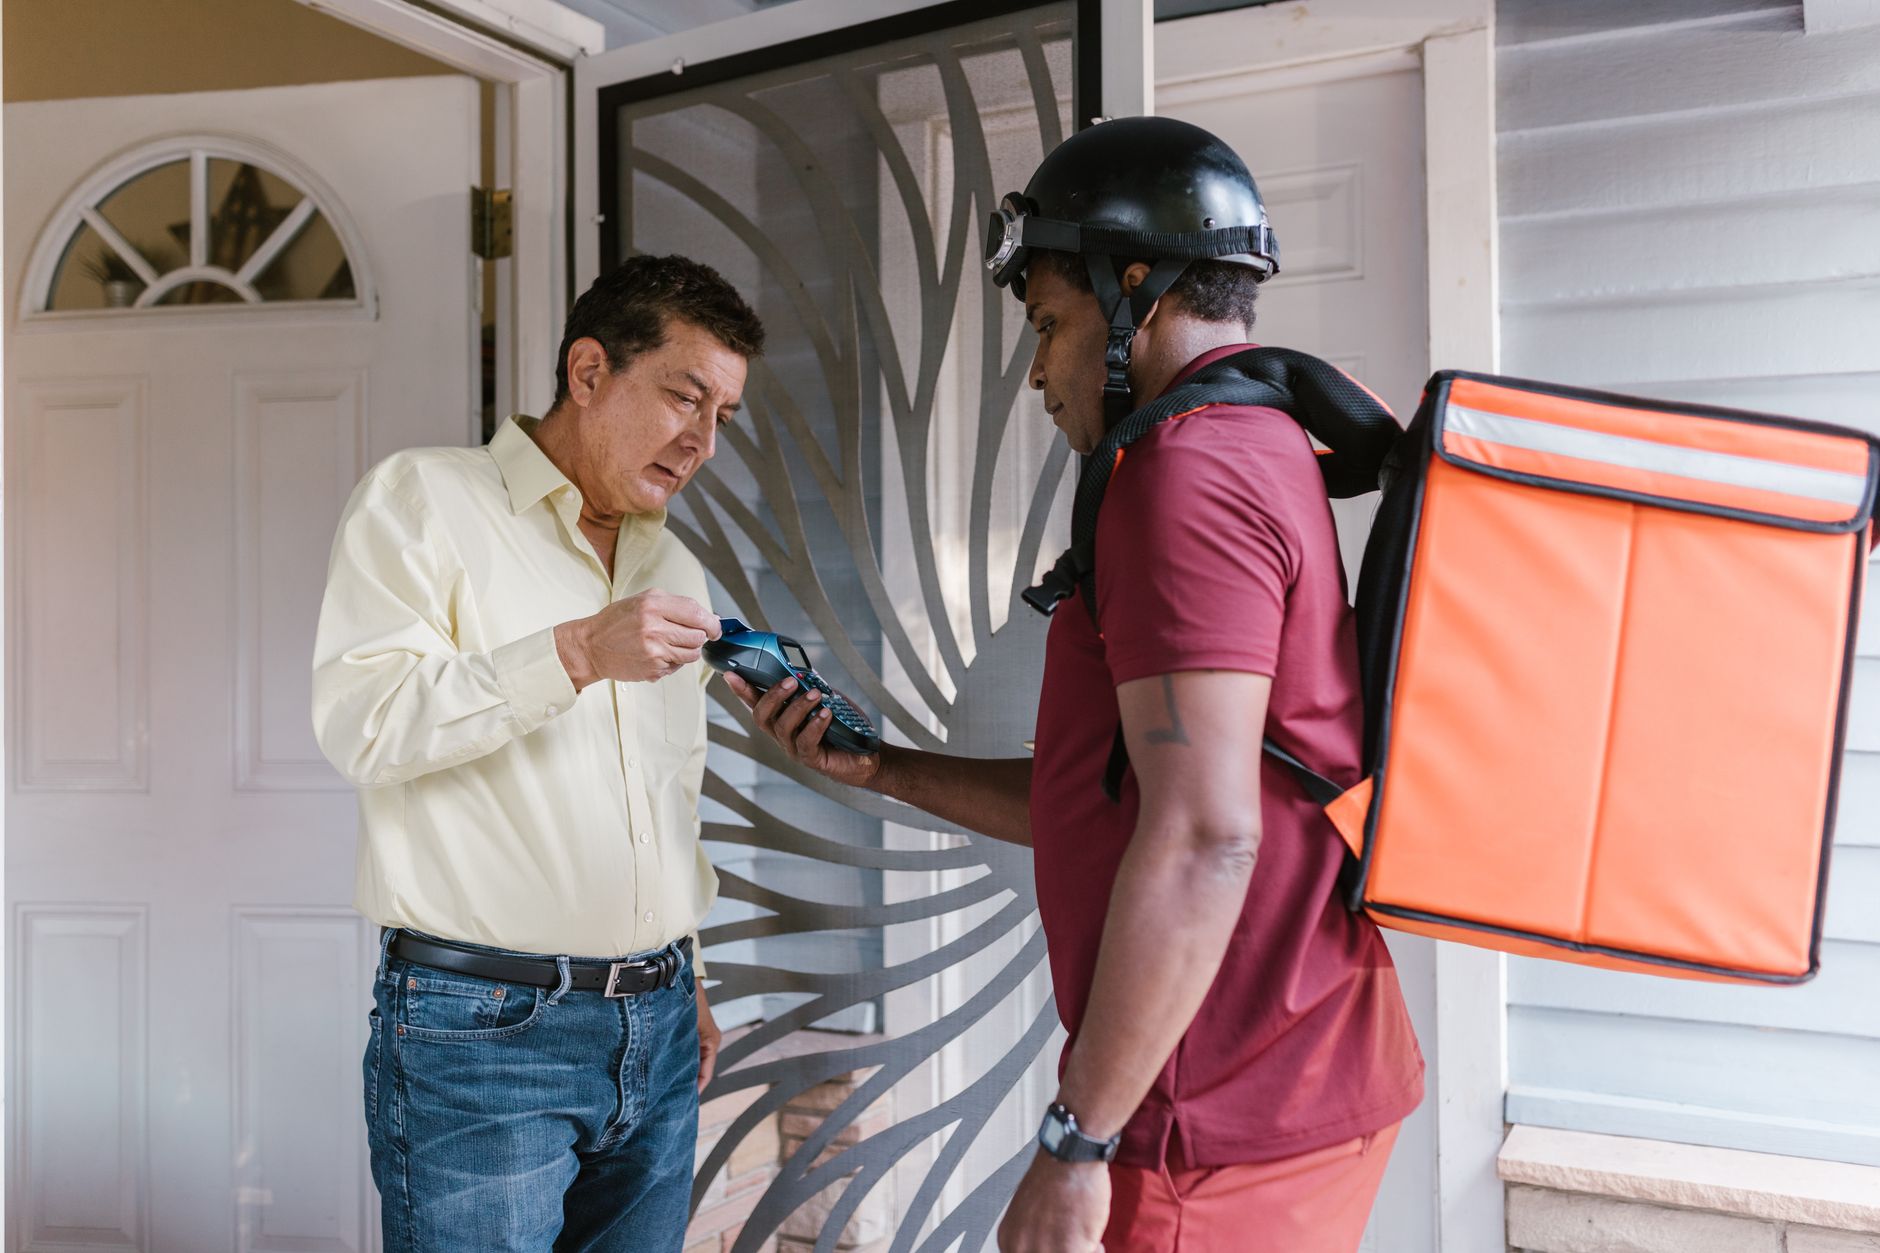
- Last-Mile Delivery: With the rise of e-commerce, managing payments for last-mile delivery, including Cash on Delivery (COD), mobile payments at the doorstep, and integration with delivery apps, has become essential. Real-time payment confirmation helps streamline delivery workflows.
Benefits and Advantages
Efficient payment processing offers numerous advantages for logistics operations:
- Speed and Efficiency: Real-time payment systems significantly reduce delays in payment confirmation and settlement, facilitating quick decision-making in time-sensitive logistics operations, such as releasing goods for shipment or confirming order fulfillment. Automation of payment reconciliation saves countless hours of manual effort.
- Reduced Costs: Automated payment processing minimizes human error, reduces administrative overhead, and lowers operational costs associated with manual invoicing, paper checks, and reconciliation. Streamlined processes can also lead to fewer late payments and reduced financing costs.
- Improved Cash Flow: Streamlined payment cycles, faster settlement, and automated invoice processing enhance cash flow management, which is critical for maintaining healthy operational budgets and funding expansion in capital-intensive logistics businesses.
- Enhanced Security and Fraud Prevention: Modern payment processing solutions incorporate advanced encryption, tokenization, and fraud detection technologies (e.g., AI/ML-driven anomaly detection) to protect sensitive financial data and mitigate risks of fraud and data breaches [16]. Adherence to standards like PCI DSS is built-in.
- Better Transparency and Audit Trails: Digital payment systems provide comprehensive, auditable records of every transaction. This transparency is invaluable for financial reporting, regulatory compliance, dispute resolution, and identifying cost-saving opportunities.
- Global Reach and Flexibility: Access to diverse payment methods and multi-currency support allows logistics companies to serve international markets more effectively, accommodating various customer preferences and regulatory requirements.
Challenges and Limitations
Despite its advantages, payment processing in logistics also presents unique challenges:
- Fraud Prevention and Cybersecurity: Logistics companies handle high-value goods and significant transaction volumes, making them attractive targets for digital fraud, identity theft, and data breaches. Investing in robust security measures and continuously updating fraud detection systems is paramount, especially given the rising sophistication of cyber threats [22].
- Integration Complexity: Ensuring payment systems work seamlessly with existing complex logistics IT infrastructure, including Warehouse Management Systems (WMS), Transportation Management Systems (TMS), ERP, and Order Management Systems (OMS), can be technically challenging and costly. API-first approaches and robust integration capabilities are essential.
- Compliance and Regulation: Adhering to a myriad of financial regulations and industry standards, such as PCI-DSS for card data, KYC (Know Your Customer) and AML (Anti-Money Laundering) laws, and varying international tax regulations, is complex. Non-compliance can lead to significant fines and reputational damage.
- Currency Fluctuations and International Payments: For global logistics, managing multiple currencies, fluctuating exchange rates, and the complexities of cross-border payments (e.g., high transaction fees, slower settlement times, varying banking regulations) can significantly impact profitability and operational efficiency.
- Cost of Processing: While automation reduces some costs, transaction fees, chargeback fees, and the cost of maintaining compliant and secure payment infrastructure can be substantial, especially for businesses with high transaction volumes or low-margin products.
Best Practices
To optimize payment processing, logistics companies should adopt strategic best practices:
- Utilize Secure and Integrated Payment Gateways: Employ trusted, PCI-compliant, and encrypted systems to safeguard transaction data. Prioritize payment gateways that offer robust fraud detection tools and seamlessly integrate with existing logistics software for end-to-end visibility.
- Automate Reconciliation and Invoicing: Implement automated systems for invoice generation, payment matching, and reconciliation. This significantly reduces manual effort, minimizes errors, and provides real-time financial insights. Solutions often integrate with Purchase Order Management for vendor payments and Order Management Systems for customer payments.
- Regularly Update Technology and Security Protocols: Keep payment processing systems updated to incorporate the latest security features, compliance standards, and efficiency enhancements. This includes regularly patching software, updating encryption methods, and conducting security audits.
- Negotiate Favorable Processing Rates: Periodically review and negotiate transaction fees, interchange rates, and other costs with payment processors and acquiring banks to optimize operational expenses. Understanding the fee structure is crucial.
- Implement Robust Fraud Monitoring: Beyond basic security, implement advanced, AI-driven monitoring systems to quickly detect and address unusual transaction patterns or fraudulent activities. This proactive approach protects revenue and customer trust [16].
- Offer Diverse Payment Options: Provide a variety of payment methods (credit cards, debit cards, bank transfers, mobile wallets) to cater to diverse customer preferences and international requirements, reducing cart abandonment and friction.
- Maintain Compliance Rigorously: Establish clear internal processes and conduct regular training to ensure continuous adherence to PCI DSS, KYC, AML, and other relevant financial regulations. Partner with compliant payment providers.
Case Studies
Many logistics companies have effectively enhanced their payment processing systems through strategic implementations:
- XPO Logistics: By adopting a comprehensive, cloud-based freight payment management system, XPO Logistics improved its cash flow by 30% and achieved greater visibility into freight spend. This allowed for better investment in technological upgrades and strategic decision-making based on accurate, real-time financial data [23].
- DHL: Implemented an automated global payment solution that significantly reduced invoice processing time from weeks to days, achieving greater accuracy and control over payment cycles for their vast network of carriers and suppliers. This automation, leveraging AI for invoice matching, resulted in substantial cost savings and improved overall operational efficiency across their global logistics network.
- Maersk: Facing challenges with manual processes for invoicing and payments for ocean freight, Maersk transitioned to a digitized, integrated payment platform. This not only streamlined the billing of complex demurrage and detention charges but also enhanced customer experience by offering more transparent and flexible payment options, reducing disputes and improving cash collection [24].
Future Trends
Looking forward, the landscape of payment processing in logistics is expected to continue evolving at a rapid pace, driven by technological innovation and changing customer expectations:
- Blockchain Technology and Decentralized Finance (DeFi): Blockchain offers the potential for highly transparent, immutable, and secure transaction records, revolutionizing payment processing by reducing fraud and intermediaries. Smart contracts could automate payments upon delivery confirmation, improving trust and efficiency in cross-border logistics [25]. While not yet mainstream for high-volume transactions, its adoption for specific use cases like trade finance and freight payments is growing.
- AI and Machine Learning: These technologies will continue to enhance transaction monitoring, risk assessment, and fraud prevention, making systems more secure and efficient. AI can also automate invoice matching, predict payment delays, and optimize payment routing to minimize costs [16].
- Mobile Payments and Digital Wallets: The growing use of mobile devices for transactions will continue to push logistics companies to adapt to and integrate mobile payment solutions into their systems, particularly for last-mile delivery and B2C interactions. Contactless payments are becoming the norm globally.
- API-First Payment Orchestration: Instead of relying on single payment processors, logistics firms will increasingly leverage API-driven payment orchestration platforms. These platforms allow businesses to connect to multiple payment gateways, processors, and alternative payment methods through a single integration point, offering greater flexibility, redundancy, and cost optimization [26].
- Embedded Finance: Financial services will become seamlessly integrated into logistics platforms, allowing for instant financing options, automated insurance, and flexible payment terms directly within the operational workflow, rather than as separate transactions. This blurs the lines between logistics and financial services, creating a more cohesive user experience.
- Real-time Payments Infrastructure Expansion: The global rollout of real-time payment networks (e.g., FedNow, RTP network in the US, UPI in India, SEPA Instant in Europe) will continue to accelerate, making instant settlement the norm for an increasing number of transactions, which will be transformative for liquidity management in logistics.
In conclusion, effective payment processing is integral to the logistics sector's operational efficiency, financial health, and customer satisfaction. As technology advances, embracing these innovations will be key for logistics companies to remain competitive and resilient in an increasingly interconnected and dynamic global economy.
Sources
- Visual Inventory Management System
- Order Management System
- Pick, Pack, Ship Software
- Purchase Order Management
- Terms of Service
- Privacy Policy
- Online Etymology Dictionary - Payment
- Merriam-Webster - Payment
- History of Payment Processing
- A Brief History of Money and Banking
- Diners Club International - History
- The History of Electronic Funds Transfer
- The History of EDI
- PayPal History: A Timeline of the Digital Payment Giant
- A Brief History of PCI DSS
- AI and Machine Learning in Payments: Overview and Trends
- What is a payment gateway?
- What is a Merchant Account?
- Real-time Payments: What Are They, and Why Are They Important?
- The Importance of Payment Processing in E-Commerce
- Freight Audit and Payment
- Cybersecurity in Logistics and Supply Chain: Challenges and Solutions
- XPO Logistics invests in cloud-based platform to improve operations
- Maersk enhances digital payment experience with new online options
- Blockchain in Logistics: Reshaping the Supply Chain
- Payment Orchestration: What Is It and Why Do You Need It?
- What Is Cash Flow and How Does It Work?
- What is Embedded Finance?
- Integrations
- Order Management System
- Purchase Order Management
- Visual Inventory Management System
- Pick, Pack, Ship Software
- Mobile WMS Overview